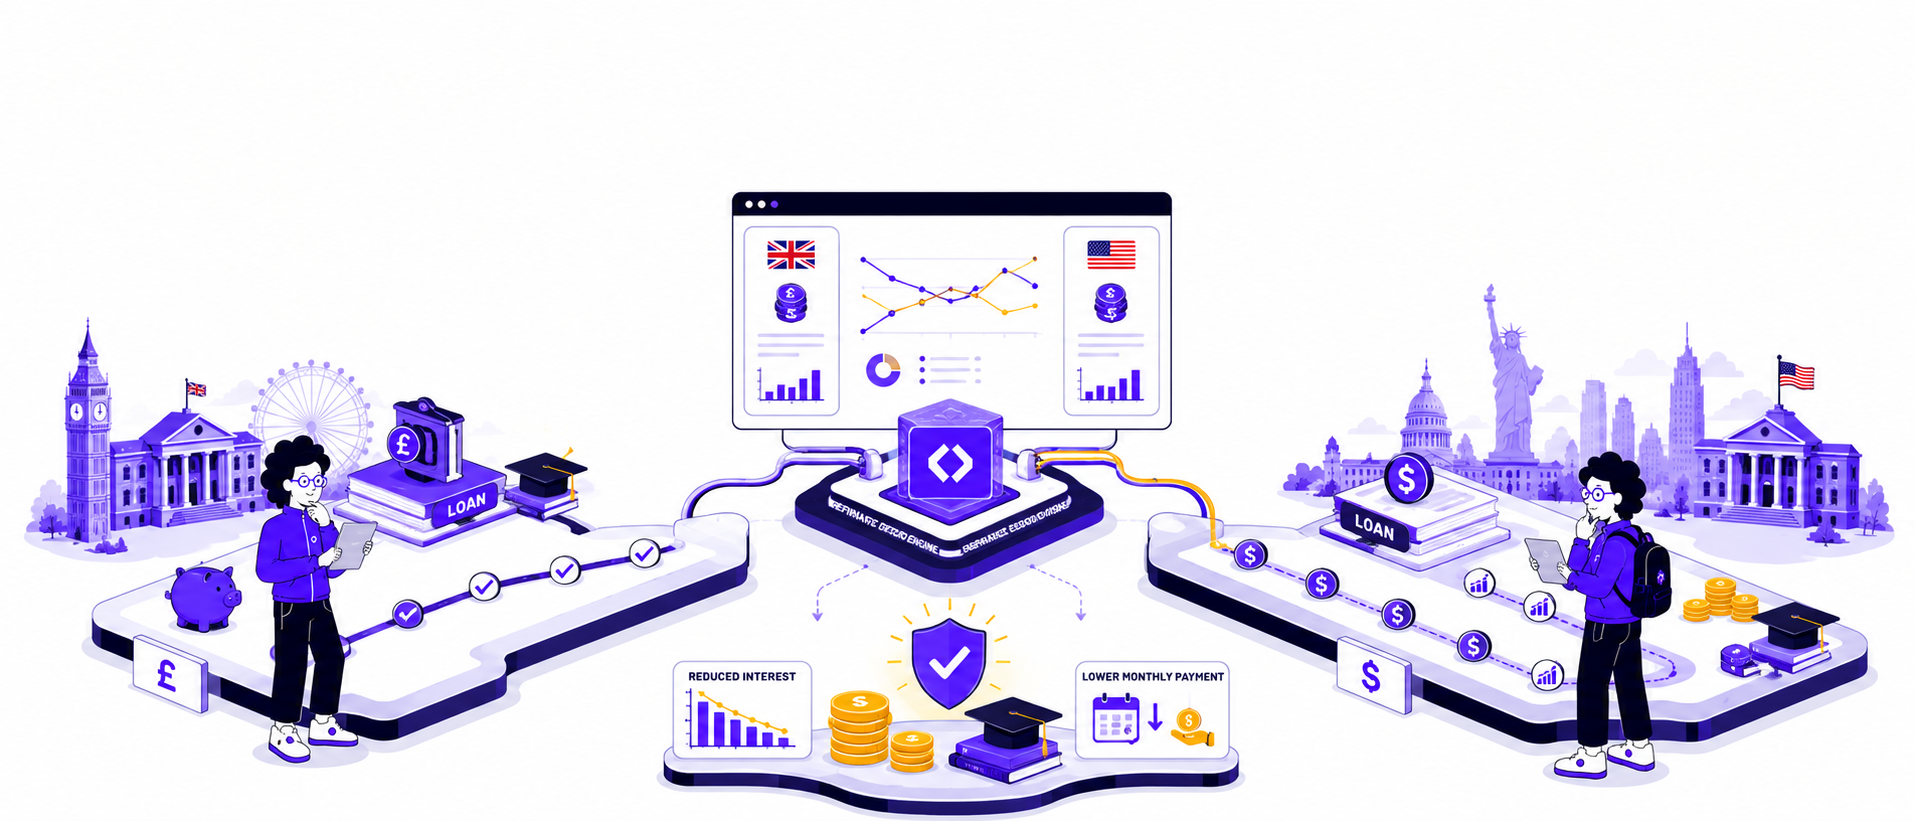
Refinancing UK vs USA education loans for Indian students works differently because the two loans are structured differently from the start. A UK education loan is typically smaller, shorter in tenure, and repaid sooner, while a USA education loan is usually larger, carries a longer moratorium, and accrues more interest before repayment even begins. Those differences directly shape when refinancing makes sense, how much it can save you, and which lenders are worth approaching.
In this guide, you’ll learn:
- How UK vs USA education loans for Indian students differ in structure and cost
- When refinancing makes sense for each loan type
- How much you can realistically save by refinancing either loan
- What lenders look for before approving a refinance
- Mistakes to avoid when comparing UK vs USA education loans for Indian students before refinancing
How do UK and USA education loans differ for Indian students?
UK vs USA education loans for Indian students differ mainly in loan size, moratorium length, and total interest accrued, because UK programs are usually one year and USA programs are usually two.
| Factor | UK Education Loan | USA Education Loan |
| Typical loan amount | Often smaller (1-year Master’s); exact amounts vary widely by university and lender | Often larger (2-year Master’s); exact amounts vary widely by university and lender |
| Course duration | Many UK Master’s programmes are 1 year | Many US Master’s programmes are 2 years |
| Moratorium length | Varies by lender and product; not automatically tied to course length | Varies by lender and product; not automatically tied to course length |
| Interest accrual period | Varies by lender and product | Varies by lender and product |
| Typical interest rate | Varies by lender and profile; check current rates directly | Varies by lender and profile; check current rates directly |
| Post-study work visa | Graduate Route: 2 years if applied by 31 Dec 2026, 18 months from 1 Jan 2027 | OPT: 12 months, plus 24-month STEM extension for eligible fields |
Note: Collateral requirements are lender-specific and tiered rather than a single fixed cutoff. Under India’s IBA Model Education Loan Scheme framework, loans up to Rs 4 lakh are generally fully collateral-free, loans between Rs 4 lakh and Rs 7.5 lakh may need a third-party guarantee, and loans above Rs 7.5 lakh generally require tangible collateral under this specific framework. Individual bank and NBFC policies may differ from this model scheme, so always confirm the exact tier and requirement with your specific lender.
The rate ranges look similar on paper, but the real difference between UK vs USA education loans for Indian students shows up in total interest paid before repayment starts. A longer study or repayment-deferral period can result in interest accruing for longer, depending on the lender and loan terms. Headline rates alone don’t tell the full story here, and that’s worth keeping in mind through the rest of this comparison.
Why the UK loan usually costs less in total interest
A shorter course means a shorter moratorium and less time for interest to compound before EMIs begin, which is one of the underappreciated differences between the two loan types.
Why a larger USA loan can carry more refinancing potential
Because a USA loan tends to be larger and accrue more interest over a longer moratorium, there can be more room for refinancing to make a meaningful dent in total cost, when that’s the case for your specific loan. A two to three percentage point rate cut on a larger loan generally saves more in absolute terms than the same rate cut on a smaller loan, simply due to the difference in principal.
When does refinancing make sense for a UK education loan?
The timing question is one of the most practical parts of this comparison, since a UK program’s shorter timeline changes when refinancing becomes worthwhile.
Right after graduation, if you’re employed in the UK
UK students often start working sooner, sometimes within months of finishing a one-year course. The Graduate Route visa currently allows up to 2 years of post-study work, but this changes for new applicants from 1 January 2027, when it drops to 18 months for most graduates (PhD graduates keep 3 years). If you have a UK job offer or have started one, refinancing into a UK-income-linked product, or negotiating a lower rate with your Indian lender once you have payslips to show, is worth pursuing as early as possible, since a shorter post-study work window also means less time to build the income history a refinance lender wants to see.
If you’re returning to India instead
If the UK job market doesn’t work out and you return to India, many lenders will want to see a couple of months of INR salary slips before considering a refinance, though exact requirements vary by lender. Because the UK loan tends to be smaller, the absolute savings from refinancing may be lower than for a larger USA loan, but the shorter timeline to repayment means it’s worth acting on sooner rather than later.
When does refinancing make sense for a USA education loan?
During OPT, or after securing H-1B or another qualifying status
If you’re earning in the US through OPT or have secured an H-1B, refinancing into a product that accounts for USD income, or negotiating a better rate with your existing lender using US pay stubs, can meaningfully reduce your total interest given the larger loan size typical of USA programs.
If you return to India without a US job
This is the scenario where refinancing matters most for USA borrowers, because USA loans tend to be larger with more accrued interest, and the gap between a US-anchored EMI and an INR salary is usually wider. Refinance as soon as you have a verifiable INR income; many lenders look for a few months of steady income before approving, so check your specific lender’s requirement before assuming a fixed timeline.
How much can you actually save by refinancing?
The savings differ significantly between the two loan types because of size and accrued interest, which is the financial core of this comparison. Seeing the numbers side by side makes the gap clear.
| Loan Type | Original Terms | Refinanced Terms | Approximate Total Interest Saved |
| UK loan, Rs 30 lakh | 12% over 7 years | 9% over 7 years | Rs 4-5 lakh |
| USA loan, Rs 60 lakh | 12% over 10 years | 9% over 10 years | Rs 10-12 lakh |
These are illustrative assumptions to show how the math works, not typical or guaranteed outcomes for UK or USA loans specifically. Actual savings depend on your outstanding balance, remaining tenure, processing fees, and the specific terms a lender offers you. A larger loan can result in higher absolute savings from the same rate cut simply because the principal is bigger, but a smaller loan refinance can still meaningfully reduce your total interest, even if the absolute number is smaller.
What lenders look for before approving a refinance
Regardless of which loan type you’re refinancing, eligibility comes down to a similar checklist:
- Demonstrated income: Many lenders want to see a couple of months of recent salary slips, in GBP, USD, or INR, though the exact requirement varies by lender.
- Clean repayment history: No missed EMIs and no NPA classification on the original loan.
- Updated employment documentation: Offer letter, appointment letter, or payslips showing current employer and salary.
- Existing loan statement: Outstanding principal, accrued interest, and current rate from your original lender.
- Co-applicant details: If a parent co-signed, their financial profile may still factor into the refinanced loan’s approval.
Mistakes to avoid when comparing UK vs USA education loans for Indian students
These mistakes show up repeatedly when students weigh UK vs USA education loans for Indian students without factoring in how refinancing changes the total cost picture.
- Assuming a lower headline rate means a cheaper loan: A UK loan and USA loan can carry the same quoted rate, but total interest paid depends heavily on moratorium length and loan size.
- Waiting until after a missed payment to consider refinancing: This is true regardless of loan type. Eligibility gets harder, not easier, once a payment has been missed.
- Ignoring currency mismatch: A USA loan repaid from an INR salary, or a UK loan repaid from a USD salary, carries exchange rate risk that refinancing into a currency-matched product can reduce.
- Not comparing total interest, only EMI size: A longer tenure lowers the EMI but can increase total interest paid, an important nuance in any UK loan refinance or USA loan refinance decision.
- Forgetting collateral implications: Refinancing can sometimes release pledged collateral earlier, but only if you ask the new lender about this explicitly.
- Ignoring the UK’s 2027 Graduate Route change: If you’re a UK graduate planning your refinancing timeline around post-study work income, factor in that the visa window is shrinking to 18 months for applications from 1 January 2027, which may shorten the period available to build UK work experience before a decision on staying or returning affects your refinancing plan.
Which loan should you refinance first, if you have both?
Some students take a UK loan for an undergraduate exchange or shorter program and a USA loan for a subsequent master’s, ending up with both running simultaneously. This is one of the less common but real scenarios in education loan refinancing.
There’s no universal rule for which to refinance first; it depends on your outstanding balance on each loan, the rate difference you can get, remaining tenure, processing fees, and your currency exposure on each loan. As a starting point for comparison, a loan with a larger outstanding balance and a bigger rate gap typically offers more absolute savings potential from refinancing, so it’s worth running the numbers on both loans before deciding which to tackle first. You can also consolidate both if a single lender offers competitive terms across currencies.
Also Read: Fixed vs Variable Rate Student Loan Refinancing: Which Is Better for Indian Students?
Also Read: Does Refinancing Student Loans Hurt Your Credit Score?
From evaluation to final selection
At GradRight, we help students compare refinancing offers across 18+ lending partners and understand what the real savings look like once factors like moratorium period, accrued interest, and current income are taken into account.
Loan decisions often become complex when multiple lenders, repayment structures, and currencies are involved, and that’s exactly where we simplify things. We support you at every stage, starting from evaluating available loan and refinancing options, to understanding trade-offs between different offers, and finally selecting a structure that best fits your financial situation.
The goal is simple: bring clarity to complex choices so you can make confident, well-informed decisions.
Compare refinancing offers side by side: Start on GradRight
 Australia
 Canada
 France
 Germany
 India
 Ireland
 UAE
 United Kingdom
 United States